For many pension scheme members, retirement can seem a long way off. However, one of the most effective ways to improve your retirement benefits is by making Additional Voluntary Contributions (AVCs). AVCs can help you build a larger retirement fund while also benefiting from valuable Income Tax relief.
With important tax relief deadlines approaching, now may be an ideal time to consider whether making an AVC could benefit your long-term financial future.
What is an AVC?
An Additional Voluntary Contribution (AVC) is an extra contribution you choose to make towards your pension, over and above your normal pension contributions.
AVCs allow you to increase your retirement savings while potentially receiving Income Tax relief at your marginal tax rate, subject to Revenue limits. You can find further information on pension contribution tax relief on the Revenue website. Revenue currently allows qualifying pension contributions to receive tax relief based on age-related limits and earnings thresholds.
Put simply, instead of taking all of your income today, you are choosing to invest some of it towards your future retirement.
Why Consider Making AVCs?
1. Build a Bigger Retirement Fund
The most obvious benefit is that you are increasing the amount being saved for your retirement.
AVCs can be particularly valuable if:
• You started contributing to a pension later in your career.
• You have gaps in your pension history.
• You want greater financial security in retirement.
• You wish to supplement your expected retirement benefits.
Even relatively modest additional contributions can make a meaningful difference over time through long-term investment growth compounding.
2. Benefit from Income Tax Relief
One of the key attractions of AVCs is the potential Income Tax relief available on qualifying contributions.
While employee pension contributions do not attract PRSI or USC relief, they may qualify for Income Tax relief at your highest rate of tax, subject to the relevant limits.
Example 1 – Higher Rate Taxpayer
• AVC contribution: €1,000
• Income Tax relief at 40%: €400
• Effective cost to you: €600
Example 2 – Standard Rate Taxpayer
• AVC contribution: €1,000
• Income Tax relief at 20%: €200
• Effective cost to you: €800
Example 3 – Larger Contribution
• AVC contribution: €5,000
• Income Tax relief at 40%: €2,000
• Effective cost to you: €3,000
In other words, a higher-rate taxpayer could potentially invest €5,000 towards retirement at an after-tax cost of €3,000, subject to Revenue rules and contribution limits.
How Much Can I Contribute?
Revenue’s age-related limits determine how much of your pension contributions can qualify for Income Tax relief. The current limits are:
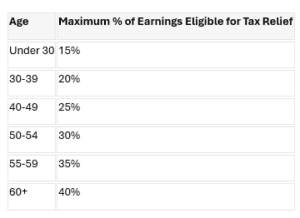
Earnings used to calculate relief are currently capped at €115,000 per annum. Existing personal pension contributions and AVCs count towards these limits.
Example
A member aged 42 earning €40,000 per year may be eligible for tax relief on qualifying pension contributions of up to €10,000 annually (25% of earnings), subject to their existing pension contributions.
Important 2026 Tax Relief Deadlines
Many people are unaware that it may be possible to make a qualifying pension contribution in 2026 and elect to claim tax relief against their 2025 income, provided the contribution is made by the relevant deadline.
For the 2025 tax year:
• 31 October 2026 is the standard Pay and File deadline.
• 18 November 2026 is the extended deadline for taxpayers who qualify for and use the Revenue Online Service (ROS) to both pay and file electronically.
When Should You Consider an AVC?
AVCs may be worth considering if:
• You have spare disposable income or savings available.
• You have received a bonus and would like to direct some of it towards retirement.
• You are concerned your current pension may not provide the level of retirement income you want.
• You started pension saving later than planned.
• You are approaching retirement and would like to maximise available tax relief opportunities.
In a Nutshell
AVCs can be one of the most tax-efficient ways to increase your retirement savings. They provide an opportunity to enhance your future pension benefits while potentially reducing your Income Tax liability today.
As the 2026 pension tax relief deadlines approach, now is a good time to review your pension position and determine whether an AVC could help you meet your retirement goals.
Need Help?
The pensions team at LHK can help you understand:
• How much you can contribute.
• The tax relief available to you.
• Whether an AVC is appropriate for your circumstances.
• How AVCs fit into your overall retirement planning strategy.
Book a call with our financial advisors here.